WEEKLY INSIGHTS

October 5, 2026
Download PDF

Author: Megan Horneman | Chief Investment Officer

Key Takeaways:

  • Global equities end the quarter in positive territory despite September sell-off.
  • Fed raises rates for the first time since 2023.
  • Inflation remains sticky.
  • Tech trade resumes leadership in 3Q.
  • Global bond yields rise sharply in 3Q.

3Q26 Market Recap – September Sell Off Fails to Ruin Entire Quarter

Despite the first Fed rate hike since 2023, surging bond yields, sticky inflation, and high oil prices, the MSCI AC World Index was able to post a modest gain in the third quarter. This was despite September living up to its historically weak reputation as volatility surged and global equities saw their second-worst month this year. In this Weekly Insights, we offer a review of 3Q26 from an economic and asset class perspective.

  • Fed raises rates: The Federal Reserve unanimously agreed to raise its benchmark rate to a range of 3.75-4.00% in September. The committee noted that “inflation remains elevated.” In addition, the rate hike “will support a timelier return to 2% inflation.”
  • Inflation remains elevated. Inflation, at the core level, as measured by the Consumer Price Index and PCE Core is growing 2.4% and 3.0%, respectively on a year over year basis.
  • Manufacturing strong. As the AI build out continues, the ISM Manufacturing Index has been in expansion territory for the past nine consecutive months.
  • Consumer continues to spend: Retail sales have been surprisingly resilient in the face of rising energy prices. Core retail sales grew at the fastest month over month pace since December 2024 in 3Q.
  • Housing gets hit: Housing data has struggled with higher home prices and soaring mortgage rates. The 30YR mortgage rate finished the quarter at the highest level (7.3%) since 2023.
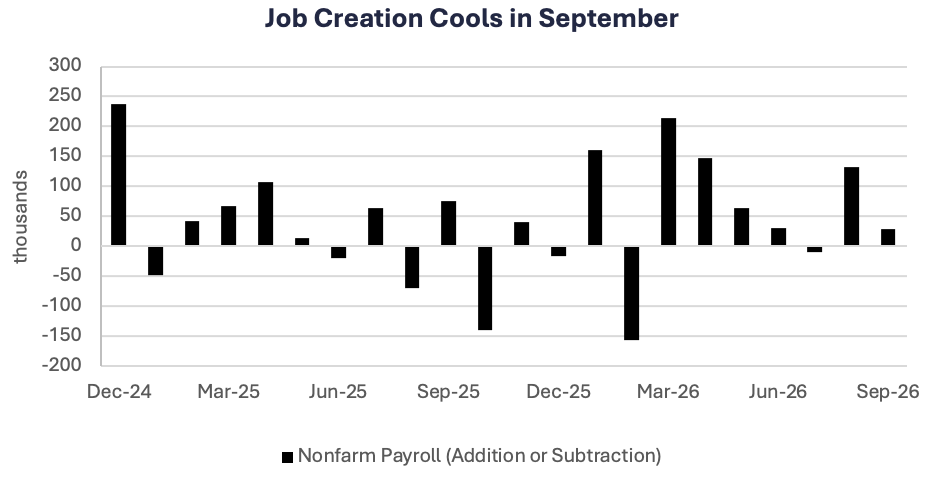
  • Labor market cools: The U.S. economy added only 29K jobs in September and the unemployment rate ticked higher (to 4.2%).

Global equities: Near record highs despite seasonal weakness: The MSCI AC World Index rallied for the second consecutive quarter as solid earnings overshadowed higher interest rates, globally.

  • Japanese equities lead: The MSCI Japan Index led the global rally. Japanese banks led the gains as the Bank of Japan raised interest rates for the second time this year.
  • Concentration in the U.S.: The resumption of the tech trade won out in 3Q as the Russell 1000 Index outperformed the Russell 2000 by 903 bps in 3Q. In addition, while the Nasdaq (+2.6%) and S&P 500 (+2.3%) rallied, the S&P 500 Equal Weight Index declined (-1.9%).

Global bonds: A global bond sell off: The Bloomberg Aggregate Index posted its worst quarterly decline since the COVID induced inflation period in 2022. Surging debt and stickly inflation led to the weakness.

  • Long term bond yields surge: The weakness was led by long term bonds as the 30YR Treasury yield rose to the highest yield since 2002, the German 30YR to the highest since 2011 and the Japanese 10YR since 1996.
  • Municipals fall sharply: The Bloomberg Managed Municipal Index posted its third worst quarterly decline on record as demand fell on surging yields.

Commodities:  The Bloomberg Commodity Index rose for the second quarter this year as geopolitical tensions supported prices.

  • Energy leads gains: Energy was the biggest beneficiary of the ongoing war with Iran.
LISTEN NOW: Markets With Megan

Your Economic and Market Detailed Recaps

  • Fed’s preferred indicator unchanged.
  • Manufacturing prices jump.
  • Labor market cools in September.
  • Global equities fall on weak U.S. data.
  • Bonds fall despite odds of an imminent rate hike falling.
  • Crude oil takes a breather as emergency supply is released.

Weekly Economic Recap — SInflation Unchanged; Labor Market Cools

Consumer confidence as measured by the Conference Board fell to the lowest level since 2014 in September. Both confidence on the present situation and future conditions declined. Consumer confidence in the labor market fell to the lowest level since 2021 (jobs plentiful vs. jobs hard to get).

Job openings as measured by the JOLTS report showed job openings fell to the lowest level in five months in August. However, layoffs fell to the lowest level since March 2025. The quits rate which measures those voluntarily leaving their job is at the lowest level since 2020.

The Fed’s preferred inflation indicator (i.e., PCE Core YoY) remained unchanged on a year over year basis in September (+3.0% YoY). However, the super core measure which includes services but excludes housing is rising 3.5% on a year over year basis.

Personal spending exceeded personal income in August which drove the personal savings rate to the lowest level since 2022.

Manufacturing as measured by the ISM Manufacturing Index dipped slightly in September but has been in expansion territory (a level above 50) for the past nine consecutive months. The weakness was driven by export orders while prices paid jumped to a four month high.

The U.S. economy added fewer jobs than anticipated in September  (+29K vs. +90K). In addition, the unemployment rate rose modestly (+4.2% vs. 4.1%). The weakness was concentrated in government, temporary workers and information services jobs.

Weekly Market Recap — Global Equities Fall on Weak U.S. Data

Equities:

The MSCI AC World Index declined last week as a rally in U.S. tech failed to lift the broader market. U.S. equities declined as a weak jobs report fueled fears of an economic slowdown. The Nasdaq and the Russell 1000 Growth rallied for the week as strong earnings fueled a rebound in semiconductor names. Europe and the UK led the global decline on rising bond yields and economic uncertainty.

Fixed Income:

The Bloomberg Aggregate Index fell for the fifth consecutive week despite odds for a rate hike in October declining on the weak jobs report. Long term Treasuries and EM debt led the drop in fixed income. Municipal bonds rebounded after six consecutive weekly declines as higher yields drew demand.

Commodities/FX:

The Bloomberg Commodity Index posted its worst weekly drop in nine weeks led by crude oil. Crude oil declined after the release of crude and diesel emergency stockpiles. Copper posted its worst week since March on a strong U.S. dollar and concern about demand slowing in China.

Q3 2026 market recap; global bond sell-off


Footnotes: Data is as of September 2026.
Data Source: Bloomberg Finance LP, Verdence Capital Advisors.


Frequently Asked Questions:

Did the Fed raise interest rates in Q3 2026?

Yes. In September 2026, the Federal Reserve unanimously raised its benchmark rate to a range of 3.75% to 4.00%, its first rate hike since 2023. The committee noted that inflation “remains elevated” and said the hike “will support a timelier return to 2% inflation.”

Why did bond yields rise in the third quarter of 2026?

Surging debt and sticky inflation drove a global bond sell-off in Q3 2026. Long-term bonds led the decline. The 30-year Treasury yield rose to its highest level since 2002, the German 30-year yield to its highest since 2011 and the Japanese 10-year yield to its highest since 1996.

How did global stocks hold up in Q3 2026?

Global equities posted a modest gain in Q3 2026, the second consecutive quarterly rally for the MSCI AC World Index, as solid earnings overshadowed higher interest rates. Japanese equities led the global rally, driven by bank stocks after the Bank of Japan raised rates for the second time this year.

Why was September 2026 a weak month for stocks?

September lived up to its historically weak reputation in 2026. Volatility surged, and global equities had their second weakest month of the year. Despite the September sell-off, global stocks still finished the third quarter with a modest gain.

What was the U.S. inflation rate in Q3 2026?

Core inflation remains above the Fed’s 2% target. Core CPI is growing 2.4% year over year, and core PCE, the Fed’s preferred inflation measure, is growing 3.0%. The “super core” measure, which includes services but excludes housing, is rising 3.5% year over year.

Is the U.S. labor market slowing down?

Yes, the labor market is cooling. The U.S. economy added only 29,000 jobs in September 2026, below the 90,000 expected, and the unemployment rate rose to 4.2% from 4.1%. Job openings fell to a five-month low in August, and the quits rate is at its lowest level since 2020.

How high are mortgage rates in 2026?

The 30-year mortgage rate finished Q3 2026 at 7.3%, its highest level since 2023. Higher home prices and rising mortgage rates weighed on housing data throughout the quarter.

Why did commodity prices rise in Q3 2026?

Geopolitical tensions supported commodity prices in Q3 2026, and the Bloomberg Commodity Index rose for the second quarter this year. Energy led the gains as the largest beneficiary of the ongoing war with Iran.

Disclaimer: © Verdence Capital Advisors, LLC

Reproduction without permission is not permitted. The indexes presented are unmanaged portfolios of specified securities and do not reflect any initial or ongoing expenses nor can it be invested in directly. An investment’s portfolio may differ significantly from the securities in the index.  This material was prepared by Verdence Capital Advisors, LLC (“VCA” or “we”, “our”, “us”). VCA believes the information and data in this document were obtained from sources considered reliable and correct and cannot guarantee either their accuracy or completeness. VCA has not independently verified third-party sourced information and data. Any projections, outlooks or assumptions should not be construed to be indicative of the actual events which will occur. These projections, market outlooks or estimates are subject to change without notice. This material is being provided for informational purposes only and is not intended to provide, and should not be relied upon for, investment, accounting, legal, or tax advice. Past performance is not a guarantee of future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product or any non-investment related content, made reference to directly or indirectly in these materials will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. You should not assume that any discussion or information contained in this report serves as the receipt of, or as a substitute for, personalized investment advice from VCA. Alternative investments are designed only for sophisticated investors who are able to bear the risk of the loss of their entire investment. Investing in alternative investments should be viewed as illiquid and generally not readily marketable or transferable. Investors should be prepared to bear the financial risks of investing in an alternative investment for an indefinite period of time. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions. All indexes are unmanaged, and you cannot invest directly in an index. Index returns do not include fees or expenses. Sector Watch Use of this website is intended for U.S. residents only. Any recommendation, opinion or advice regarding securities or markets contained in such material does not reflect the views of Verdence Capital, and Verdence Capital does not verify any information included in such material. Verdence Capital assumes no responsibility for any fact, recommendation, opinion, or advice contained in any such research material and expressly disclaims any responsibility for any decisions or for the suitability of any security or transaction based on it. Any decisions you may make to buy, sell, or hold a security based on this research will be entirely your own and not in any way deemed to be endorsed or influenced by or attributed to Verdence Capital. It is understood that, without exception, any order based on such research that is placed for execution is and will be treated as an UNRECOMMENDED AND UNSOLICITED ORDER. Further, Verdence Capital assumes no responsibility for the accuracy, completeness, or timeliness of any such research or for updating such research, which is subject to change without notice at any time. Verdence Capital does not provide tax, or legal advice. Under no circumstance is the information contained within this research to be used or considered as an offer to sell or a solicitation of an offer to buy any particular investment/security. Fixed income securities are subject to increased loss of principal during periods of rising interest rates. Fixed income investments are subject to various other risks including changes in credit quality, market valuations, liquidity, prepayments, early redemption, corporate events, tax ramifications and other factors. Lower rated securities are subject to greater credit risk, default risk, and liquidity risk. Commodity‐related products, including futures, carry a high level of risk and are not suitable for all investors. Commodity‐related products may be extremely volatile, illiquid and can be significantly affected by underlying commodity prices, world events, import controls, worldwide competition, government regulations, and economic conditions, regardless of the length of time shares are held. Data is provided for information purposes only and is not intended for trading purposes. Verdence Capital shall not be liable for any errors or delay in the content, or for any action taken in reliance on any content. Weekly Insights/Qtrly & Annual Outlook The indexes presented are unmanaged portfolios of specified securities and do not reflect any initial or ongoing expenses nor can it be invested in directly. An investment’s portfolio may differ significantly from the securities in the index. Semi-Annual Chart Pack Where shown, performance information presented is that which has been calculated and presented by an unaffiliated third-party manager. We have no insight into the performance of the advisor/product/account or fund shown and do not attempt to determine whether the performance presented is accurate. Therefore, the performance could be incorrect, overstated or not reflective of actual trading of client funds. There is the potential that the performance shown is a back test and not the result of real investment advice and trading. As such, it could not be relied upon as indicative of future returns of a particular strategy. Where performance shown is that of a pooled account, limited partnership, or private equity fund, you should be aware that there is a significant lack of transparency into the operations and investment process and investment vehicles invested in. As a result, pricing and valuation of the underlying holdings which produced the stated performance could be incorrect, stale, or overstated and therefore the performance figures presented cannot be relied upon. Before investing, we encourage you to request additional information, particularly performance information, of any product that you are considering for your client. You should read, as applicable, the Prospectus, SAI, Composite Disclosure and/or performance disclosure associated with any product that you are considering for investment for your or your client’s. Products shown may have minimum account sizes or minimum investments which may preclude retail and non-high net worth investors from being able to invest in these products. You should be aware that certain LPs may be closed to new investors and therefore your clients may be prevented from investing in these products. Portfolio Implementation and Rationales The SMA Asset Allocation Models do not represent a personalized recommendation of a particular investment strategy to you or your clients. You should not buy or sell an investment without first considering whether it is appropriate for your client’s portfolio. Additionally, you should review and consider any recent market news. All expressions of opinion are subject to change without notice in reaction to shifting market conditions. Data contained herein from third-party providers is obtained from what are considered reliable sources. However, its accuracy, completeness or reliability cannot be guaranteed. Supporting documentation for any claims or statistical information is available upon request. Examples provided are for illustrative purposes only and not intended to be reflective of results you can expect to achieve. Diversification and asset allocation do not ensure a profit and do not protect against losses in declining markets. Any forecasts contained herein are for illustrative purposes only, may be based upon proprietary research and are developed through analysis of historical public data. Investments in growth stocks may experience price volatility due to their sensitivity to market fluctuations and dependence on future earnings expectations. Sector allocation references to market capitalization (“smid cap” or “micro caps” etc.) may be subject to special risks given their characteristic narrow markets, limited financial resources, and less liquid stocks, all of which may cause price volatility. International/global investing can involve special risks, such as political changes and currency fluctuations. These risks are heightened in emerging markets. A significant percentage of the underlying investments in aggressive asset allocation portfolio investments have a higher-than-average risk exposure. You should consider your risk tolerance of each of your clients carefully before choosing such a strategy. An investment with multiple underlying investments (which may include asset-allocation or custom blended investments) may be subject to the expenses of those underlying investments in addition to those of the investment itself. Investments may reside in the specialty category due to 1) allowable investment flexibility that precludes classification in standard asset categories and/or 2) investment concentration in a limited group of securities or industry sectors. Investments in this category may be more volatile than less flexible and/or less concentrated investments and may be appropriate as only a minor component in an investor’s overall portfolio. Investment Managers You and your clients should carefully consider investment objectives, risks, charges, and expenses of Funds discussed. This and other important information are contained in the respective Fund prospectuses and summary prospectuses, which should be read carefully before investing. Investment portfolio statistics change over time. Current performance may be lower or higher than return data quoted herein. The investment return and the principal value of an investment will fluctuate; so, an investor’s shares/units, when redeemed, may be worth more or less than their original cost. Verdence relies heavily on unaudited third-party data. Data sources include public data, such as mutual fund data, and non-public data, such as information provided by other investment advisors and managers of limited partnership pooled accounts. Data and/or statistics included on this Portal, including references to performance, opinions, ratings, rankings, manager statistics and demographic information, product, or strategy descriptions, either quantitative or qualitative, are based upon information reasonably available to us as of the applicable date(s) then-published. Information has been obtained from sources that we believe to be reliable, but these sources cannot be guaranteed as to their accuracy or completeness. All data and information produced by a third party has the potential to be incorrect, incomplete, or otherwise misleading. No implication shall be created that the information contained on the Site is correct, including as of any time subsequent to the publish date, and Verdence does not undertake an obligation to update such information at any time after such date. Verdence makes not warranty or representation of the veracity of the data and information and its use of the information should not be implied as an endorsement of any material or statements made. Data, particularly non-public data, is subject to error and where the information is not audited, the potential for error is greater. Where shown, performance information presented is that which has been calculated and presented by an unaffiliated third-party manager. We have no insight into the performance of the advisor/product/account or fund shown and do not attempt to determine whether the performance presented is accurate. Therefore, the performance could be incorrect, overstated or not reflective of actual trading of client funds. There is the potential that the performance shown is a back test and not the result of real investment advice and trading. As such, it could not be relied upon as indicative of future returns of a particular strategy. Where performance shown is that of a pooled account, limited partnership, or private equity fund, you should be aware that there is a significant lack of transparency into the operations and investment process and investment vehicles invested in. As a result, pricing and valuation of the underlying holdings which produced the stated performance could be incorrect, stale, or overstated and therefore the performance figures presented cannot be relied upon. Before investing, we encourage you to request additional information, particularly performance information, of any product that you are considering for your client. You should read, as applicable, the Prospectus, SAI, Composite Disclosure and/or performance disclosure associated with any product that you are considering for investment for your or your client’s. Certain products shown may have account minimums or minimum investment sizes that are unattainable for your clients and therefore they may not be eligible to invest in these products. Reference to registration with the Securities and Exchange Commission (“SEC”) does not imply that the SEC has endorsed or approved the qualifications of Verdence or its respective representatives to provide any advisory services described on the Site.

Read more