WEEKLY INSIGHTS

September 28, 2026
Download PDF

Author: Megan Horneman | Chief Investment Officer

Key Takeaways:

  • Diesel prices have increased more than gasoline prices.
  • Diesel powers nearly every aspect of the economy.
  • Inflation is the most important risk.
  • Proposed regulation could have the opposite effect.
  • Need to see the Strait of Hormuz open to move diesel before seeing price relief.

Why Do Diesel Prices Matter?

Most of the attention on rising fuel costs due to the Iran war has been centered around gasoline prices. However, we should not ignore diesel prices as the daily national average of a gallon of diesel has increased more than regular gasoline since the war started. Diesel gases are hovering at a record high ($6.53/gallon) and have increased over 70% since the end of February, compared to the ~50% increase in gasoline prices. Before the Iran war, the Gulf and Russia made up ~45% of the world’s seaborne diesel trade, according to the International Energy Agency (IEA). In August, the IEA reported that Gulf diesel exports had fallen to just over a quarter of pre-war levels and Russia’s exports have been at a near standstill as refineries have been targeted by Ukraine. In this Weekly Insights, we look at why diesel matters, how higher prices impact the economy, and what policymakers have proposed to bring prices down.

Why does diesel matter?

Diesel powers nearly every aspect of the global economy. It powers things like trucks, machinery, rail, farm equipment and some cargo ships. The American Trucking Agency has reported that trucks and freight rail which runs primarily on diesel move ~80% of the U.S. freight tonnage.1 In addition, the American Farm Bureau Federation expects farm fuel expenses (which include diesel) to hit a record $22 billion this year.

How this impacts the economy.

Since diesel is important to the movement and production of so many items, higher prices are inflationary. How much businesses can pass onto consumers and how much they can absorb depends on margins. Some of the primary businesses that rely on diesel (e.g., truckers, farmers, manufacturers) already have thin margins so they have little ability to absorb the higher prices. They either cut production (less crop growing) which shrinks supply or pass it onto consumers. Both options are inflationary.

What policymakers have proposed.

The most talked about proposal has been to limit or even eliminate diesel exports for a specified time or until the price falls to a predetermined level. However, this could actually have the opposite effect and raise other fuel costs. A barrel of crude oil is refined to produce diesel, gas and jet fuel. If refiners do not export diesel they refine fewer barrels of crude oil because they don’t have space to store diesel. In addition, most of the diesel sits in the Gulf and pipelines to the east coast are near capacity and regulations limit shipping between U.S. ports. This is a refinery and capacity problem, not a production problem.

The Bottom Line:

In our opinion, the current proposal is unlikely to bring prices down. Diesel is priced in the global market and keeping U.S. barrels at home forces refiners to cut output, pushes gas prices higher and can strain relationships with key trading partners who rely on U.S. fuel. The only way to truly get prices down is to restore shipping through the Strait of Hormuz so we can move diesel. Until that happens, diesel prices are an inflation and margin risk for businesses. We will continue to watch refinery output and freight costs to see how long this can be an inflation and economic problem.

LISTEN NOW: Markets With Megan

Your Economic and Market Detailed Recaps

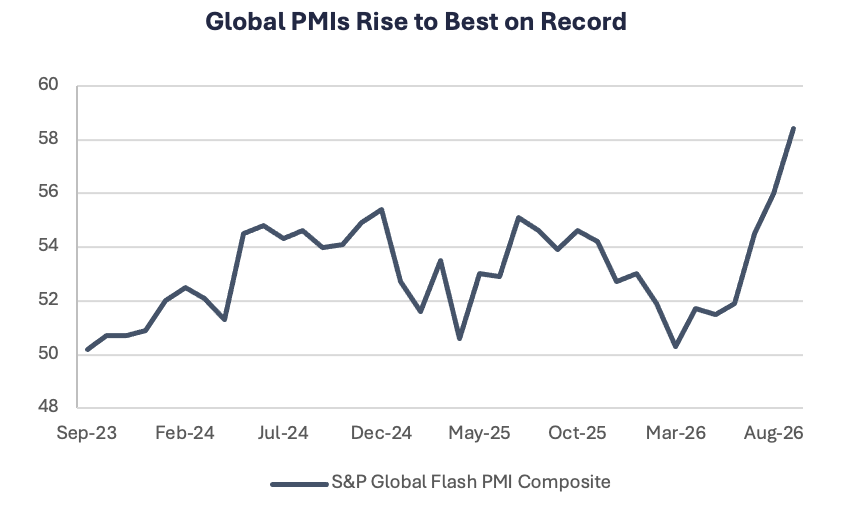
  • Flash PMIs jump at a record pace.
  • New home sales strongest seen this year.
  • Core durable goods orders surging.
  • Global equities rally on economic and tech optimism.
  • Bonds fall on strong economic data.
  • Commodities dragged lower by precious metals and grains.

Weekly Economic Recap — Solid Economic Data as we Approach the End of 3Q26

The S&P Global Flash PMI showed that manufacturing and service activity surged in September. The composite index has increased for four consecutive months and both underlying components (i.e., manufacturing and services) jumped to the highest level on record (records began 2023).

The final reading on building permits for August showed that permits fell slightly less than originally reported (-2.1% vs -2.7%). Both permits for single family and multifamily homes declined for the month.

New home sales rose much more than expected in August (+6.4% MoM vs. 1.3% MoM est.) At a 684K annual pace, new home sales are rising at the fastest pace this year. The sales were strongest in the midwest and south as both the northeast and west saw sales decline. Due to the strength in sales, the months’ supply of new homes dipped to the lowest level since December 2025.

The preliminary reading on August durable goods orders showed orders were flat for the month. A steep decline in nondefense aircraft overshadowed strength in electrical equipment, machinery and metals. The core reading (goods orders nondefense and excluding aircraft) rose much more than expected (+1.6% MoM vs. 0.6% est.).

Weekly Market Recap — Global Equities Rise on Better Economic Data; Tech Rotation

Equities:

The MSCI AC World Index rose the most in seven weeks as strong U.S. economic data and positive tech news fueled risk appetite. The U.S., as measured by the S&P 500, outperformed all the major regions with the exception of the emerging markets. EM, specifically Asia ex Japan, also benefited from the rotation back to technology. Small and midcap U.S. stocks and value underperformed large caps and growth stocks.

Fixed Income:

The Bloomberg Aggregate Index fell for the fourth consecutive week as strong economic data pushed long term rates higher. The 30YR U.S. Treasury posted its worst one week decline in four months. Municipals were the second worst performing sector as Treasury yields remained volatilite and technicals remain weak.

Commodities/FX:

The Bloomberg Commodity Index fell for the first time in three weeks as gold prices were hampered by strong economic data and competition from Treasury yields. Grains, specifically wheat, were also weaker on disappointing export demand.

diesel prices


Footnotes: Data is as of September 2026.
Data Source: FactSet Research Systems, Verdence Capital Advisors.


Frequently Asked Questions:

Why are diesel prices so high right now?

As of September 2026, diesel prices have risen sharply since the Iran war began. Before the war, the Gulf and Russia made up about 45% of the world’s seaborne diesel trade, according to the IEA. By August, Gulf diesel exports had fallen to just over a quarter of pre-war levels. Russian exports were near a standstill after Ukraine targeted its refineries.

Why have diesel prices risen more than gasoline?

As of September 2026, the national average for diesel has climbed more than 70% since the end of February, to a record $6.53 a gallon. Gasoline rose about 50% over the same period. Diesel supply depends heavily on seaborne trade from the Gulf and Russia, and the war has sharply disrupted both sources.

How do diesel prices affect inflation?

Diesel powers trucks, freight rail, farm equipment, machinery and some cargo ships, so it affects the cost of producing and moving most goods. Truckers, farmers and manufacturers often run on thin margins. When fuel costs rise, they may cut production or pass the cost to consumers. In Verdence’s view, both paths are inflationary.

How much U.S. freight moves on diesel?

Trucks and freight rail, which run primarily on diesel, move about 80% of U.S. freight tonnage. That figure comes from the most recent annual American Trucking Associations report, released in 2024. Because so much freight depends on diesel, higher diesel prices tend to show up in costs across the economy.

Would banning diesel exports lower U.S. fuel prices?

In Verdence’s view, limiting or banning diesel exports is unlikely to bring prices down. Diesel is priced in the global market. Refiners that can’t export diesel have limited storage, so they may refine fewer barrels of crude. That could push gasoline prices higher and strain relationships with trading partners that rely on U.S. fuel.

Why is it hard to move diesel to the East Coast?

Most U.S. diesel sits in the Gulf region. Pipelines to the East Coast are near capacity, and regulations limit shipping between U.S. ports. Verdence describes this as a refining and capacity problem. U.S. production isn’t the constraint. The bottleneck is getting refined diesel from where it is made to where it is needed.

What would bring diesel prices down?

In Verdence’s view, the clearest path to lower diesel prices is restoring shipping through the Strait of Hormuz so diesel can move again. Until that happens, diesel prices may remain an inflation and margin risk for businesses. Verdence is watching refinery output and freight costs to gauge how long the pressure may last.

How much are farmers spending on fuel this year?

As of September 2026, the American Farm Bureau Federation expects farm fuel expenses, which include diesel, to reach a record $22 billion this year. Farmers typically operate on thin margins. Higher fuel costs may lead them to grow less or to pass the cost on through higher prices, and either path adds to inflation.
Disclaimer: © Verdence Capital Advisors, LLC

Reproduction without permission is not permitted. The indexes presented are unmanaged portfolios of specified securities and do not reflect any initial or ongoing expenses nor can it be invested in directly. An investment’s portfolio may differ significantly from the securities in the index.  This material was prepared by Verdence Capital Advisors, LLC (“VCA” or “we”, “our”, “us”). VCA believes the information and data in this document were obtained from sources considered reliable and correct and cannot guarantee either their accuracy or completeness. VCA has not independently verified third-party sourced information and data. Any projections, outlooks or assumptions should not be construed to be indicative of the actual events which will occur. These projections, market outlooks or estimates are subject to change without notice. This material is being provided for informational purposes only and is not intended to provide, and should not be relied upon for, investment, accounting, legal, or tax advice. Past performance is not a guarantee of future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product or any non-investment related content, made reference to directly or indirectly in these materials will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. You should not assume that any discussion or information contained in this report serves as the receipt of, or as a substitute for, personalized investment advice from VCA. Alternative investments are designed only for sophisticated investors who are able to bear the risk of the loss of their entire investment. Investing in alternative investments should be viewed as illiquid and generally not readily marketable or transferable. Investors should be prepared to bear the financial risks of investing in an alternative investment for an indefinite period of time. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions. All indexes are unmanaged, and you cannot invest directly in an index. Index returns do not include fees or expenses. Sector Watch Use of this website is intended for U.S. residents only. Any recommendation, opinion or advice regarding securities or markets contained in such material does not reflect the views of Verdence Capital, and Verdence Capital does not verify any information included in such material. Verdence Capital assumes no responsibility for any fact, recommendation, opinion, or advice contained in any such research material and expressly disclaims any responsibility for any decisions or for the suitability of any security or transaction based on it. Any decisions you may make to buy, sell, or hold a security based on this research will be entirely your own and not in any way deemed to be endorsed or influenced by or attributed to Verdence Capital. It is understood that, without exception, any order based on such research that is placed for execution is and will be treated as an UNRECOMMENDED AND UNSOLICITED ORDER. Further, Verdence Capital assumes no responsibility for the accuracy, completeness, or timeliness of any such research or for updating such research, which is subject to change without notice at any time. Verdence Capital does not provide tax, or legal advice. Under no circumstance is the information contained within this research to be used or considered as an offer to sell or a solicitation of an offer to buy any particular investment/security. Fixed income securities are subject to increased loss of principal during periods of rising interest rates. Fixed income investments are subject to various other risks including changes in credit quality, market valuations, liquidity, prepayments, early redemption, corporate events, tax ramifications and other factors. Lower rated securities are subject to greater credit risk, default risk, and liquidity risk. Commodity‐related products, including futures, carry a high level of risk and are not suitable for all investors. Commodity‐related products may be extremely volatile, illiquid and can be significantly affected by underlying commodity prices, world events, import controls, worldwide competition, government regulations, and economic conditions, regardless of the length of time shares are held. Data is provided for information purposes only and is not intended for trading purposes. Verdence Capital shall not be liable for any errors or delay in the content, or for any action taken in reliance on any content. Weekly Insights/Qtrly & Annual Outlook The indexes presented are unmanaged portfolios of specified securities and do not reflect any initial or ongoing expenses nor can it be invested in directly. An investment’s portfolio may differ significantly from the securities in the index. Semi-Annual Chart Pack Where shown, performance information presented is that which has been calculated and presented by an unaffiliated third-party manager. We have no insight into the performance of the advisor/product/account or fund shown and do not attempt to determine whether the performance presented is accurate. Therefore, the performance could be incorrect, overstated or not reflective of actual trading of client funds. There is the potential that the performance shown is a back test and not the result of real investment advice and trading. As such, it could not be relied upon as indicative of future returns of a particular strategy. Where performance shown is that of a pooled account, limited partnership, or private equity fund, you should be aware that there is a significant lack of transparency into the operations and investment process and investment vehicles invested in. As a result, pricing and valuation of the underlying holdings which produced the stated performance could be incorrect, stale, or overstated and therefore the performance figures presented cannot be relied upon. Before investing, we encourage you to request additional information, particularly performance information, of any product that you are considering for your client. You should read, as applicable, the Prospectus, SAI, Composite Disclosure and/or performance disclosure associated with any product that you are considering for investment for your or your client’s. Products shown may have minimum account sizes or minimum investments which may preclude retail and non-high net worth investors from being able to invest in these products. You should be aware that certain LPs may be closed to new investors and therefore your clients may be prevented from investing in these products. Portfolio Implementation and Rationales The SMA Asset Allocation Models do not represent a personalized recommendation of a particular investment strategy to you or your clients. You should not buy or sell an investment without first considering whether it is appropriate for your client’s portfolio. Additionally, you should review and consider any recent market news. All expressions of opinion are subject to change without notice in reaction to shifting market conditions. Data contained herein from third-party providers is obtained from what are considered reliable sources. However, its accuracy, completeness or reliability cannot be guaranteed. Supporting documentation for any claims or statistical information is available upon request. Examples provided are for illustrative purposes only and not intended to be reflective of results you can expect to achieve. Diversification and asset allocation do not ensure a profit and do not protect against losses in declining markets. Any forecasts contained herein are for illustrative purposes only, may be based upon proprietary research and are developed through analysis of historical public data. Investments in growth stocks may experience price volatility due to their sensitivity to market fluctuations and dependence on future earnings expectations. Sector allocation references to market capitalization (“smid cap” or “micro caps” etc.) may be subject to special risks given their characteristic narrow markets, limited financial resources, and less liquid stocks, all of which may cause price volatility. International/global investing can involve special risks, such as political changes and currency fluctuations. These risks are heightened in emerging markets. A significant percentage of the underlying investments in aggressive asset allocation portfolio investments have a higher-than-average risk exposure. You should consider your risk tolerance of each of your clients carefully before choosing such a strategy. An investment with multiple underlying investments (which may include asset-allocation or custom blended investments) may be subject to the expenses of those underlying investments in addition to those of the investment itself. Investments may reside in the specialty category due to 1) allowable investment flexibility that precludes classification in standard asset categories and/or 2) investment concentration in a limited group of securities or industry sectors. Investments in this category may be more volatile than less flexible and/or less concentrated investments and may be appropriate as only a minor component in an investor’s overall portfolio. Investment Managers You and your clients should carefully consider investment objectives, risks, charges, and expenses of Funds discussed. This and other important information are contained in the respective Fund prospectuses and summary prospectuses, which should be read carefully before investing. Investment portfolio statistics change over time. Current performance may be lower or higher than return data quoted herein. The investment return and the principal value of an investment will fluctuate; so, an investor’s shares/units, when redeemed, may be worth more or less than their original cost. Verdence relies heavily on unaudited third-party data. Data sources include public data, such as mutual fund data, and non-public data, such as information provided by other investment advisors and managers of limited partnership pooled accounts. Data and/or statistics included on this Portal, including references to performance, opinions, ratings, rankings, manager statistics and demographic information, product, or strategy descriptions, either quantitative or qualitative, are based upon information reasonably available to us as of the applicable date(s) then-published. Information has been obtained from sources that we believe to be reliable, but these sources cannot be guaranteed as to their accuracy or completeness. All data and information produced by a third party has the potential to be incorrect, incomplete, or otherwise misleading. No implication shall be created that the information contained on the Site is correct, including as of any time subsequent to the publish date, and Verdence does not undertake an obligation to update such information at any time after such date. Verdence makes not warranty or representation of the veracity of the data and information and its use of the information should not be implied as an endorsement of any material or statements made. Data, particularly non-public data, is subject to error and where the information is not audited, the potential for error is greater. Where shown, performance information presented is that which has been calculated and presented by an unaffiliated third-party manager. We have no insight into the performance of the advisor/product/account or fund shown and do not attempt to determine whether the performance presented is accurate. Therefore, the performance could be incorrect, overstated or not reflective of actual trading of client funds. There is the potential that the performance shown is a back test and not the result of real investment advice and trading. As such, it could not be relied upon as indicative of future returns of a particular strategy. Where performance shown is that of a pooled account, limited partnership, or private equity fund, you should be aware that there is a significant lack of transparency into the operations and investment process and investment vehicles invested in. As a result, pricing and valuation of the underlying holdings which produced the stated performance could be incorrect, stale, or overstated and therefore the performance figures presented cannot be relied upon. Before investing, we encourage you to request additional information, particularly performance information, of any product that you are considering for your client. You should read, as applicable, the Prospectus, SAI, Composite Disclosure and/or performance disclosure associated with any product that you are considering for investment for your or your client’s. Certain products shown may have account minimums or minimum investment sizes that are unattainable for your clients and therefore they may not be eligible to invest in these products. Reference to registration with the Securities and Exchange Commission (“SEC”) does not imply that the SEC has endorsed or approved the qualifications of Verdence or its respective representatives to provide any advisory services described on the Site.

Read more