Author: Megan Horneman | Chief Investment Officer
Key Takeaways:
- Fed raises rates for the first time since 2023.
- Inflation “too high for too long” forces the Fed to act.
- History tells us it is rarely a one and done.
- Equities can struggle in the year after the Fed starts tightening rates.
- No one wants rate hikes, but the Fed should act this week and get tough on inflation.
Rate Hike is Here – What Does it Mean?
As expected, the Federal Reserve unanimously delivered its first interest rate hike since 2023 last week, moving the Fed funds rate to a range of 3.75% to 4.00%. Equity markets initially reacted with negativity before accepting this new phase of monetary policy. We realize the Fed’s action has raised many questions. As a result, we are using this issue of our weekly insights to cover why the Fed acted now, what past rate hikes tell us, and what it may mean for equity and fixed income markets into year end.
Why now?
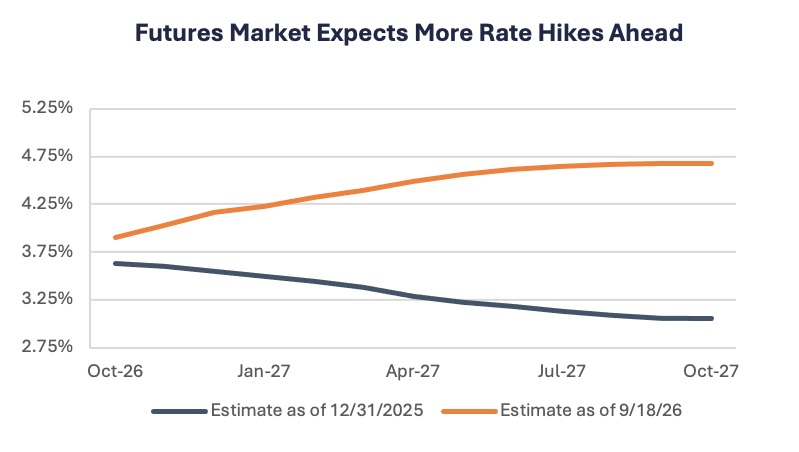
In the comments, Chairman Warsh reiterated that inflation is a bigger concern than the labor market. In addition, he said that the action from the Fed was to “remove a dose of accommodation,” suggesting more work may be needed. The committee said that inflation has been “too high for too long, running above target for more than five years.” In addition, since he took office (in May) inflation data has shown no “meaningful improvement in underlying trends.” The forecasts from FOMC members show at least one more rate hike before year end.
What history tells us?
History tells us that it is rare to just see one rate hike from the Fed. The only time where the Fed raised rates just once was in 1997 when Greenspan acted preemptively to address “irrational exuberance.” Instead the Fed usually starts a series of rate hikes. Going back to 1946, the median length of a tightening cycle is 12 months and the Fed funds rate rises on average 2.6%. In the 1970s and 1980s there were shorter cycles of hiking and cutting as the Fed battled hyperinflation and elevated unemployment. However, in more modern times (1989-2022) the tightening cycles have lasted ~14 months and the Fed raised rates by ~300 bps on average.
What to expect from equities and bonds?
If we use history as a guide and this is the start of a Fed tightening cycle (at least three rate hikes before a cut), it would tell us equity investors should be prepared for more muted returns over the next year. Since the early 1970s, on average, S. (S&P 500) and international equities (MSCI EAFE) return between 2-5% in the one year after the Fed starts raising rates. Commodities are the best performing asset class in the one year after a tightening cycle.
The Bottom Line:
We do not view the Fed’s move last week as an end to the bull market or that a recession is imminent. Instead, we believe it is a way to unwind years of unwarranted accommodative monetary policy that has done nothing to get inflation to the Fed’s target. We realize that no one wants rate hikes, but we think inflation is a much bigger risk to the economy and equity markets in the long run than the Fed raising rates. However, we do expect markets to remain volatile through year end as investors and companies absorb higher for longer interest rates. In the near term, this could put a strain on an already stressed housing market with the 30 year mortgage rate at the highest level seen in more than a year (6.97%). However, we believe this initial action by the Fed is a step in the right direction to drain some excess liquidity and try to get inflation back to the Fed’s target (2.0%).
LISTEN NOW: Markets With Megan
Your Economic and Market Detailed Recaps
- Consumer spending surges in August.
- Homebuilder sentiment falls as rate rises.
- Fed delivers the rate hike markets expected.
- Global equities decline on war and hawkish rate hike.
- Bonds fall as Fed suggests more rate hikes ahead.
- Metals support commodities instead of oil.
Weekly Economic Recap — Fed Raises Rates for First Time Since 2023
Retail sales for the month of August came in much better than expected (+1.2% MoM vs 0.8% MoM est.). While the majority of the gain at the headline level was due to higher spending on gas we saw broad based strength in spending. The areas that led the gains outside of gas were internet sales, electronics, sporting goods and furniture. The only area to see weakness was building materials.
The NAHB Housing Market Index declined to the lowest level in a year in September. Confidence in the present and future conditions of the housing market declined while prospective buyers’ traffic was unchanged. Confidence is being negatively impacted by the 30YR mortgage rate which is at the highest level in more than a year.
The Federal Reserve met and as expected increased the Fed funds rate for the first time since 2023 by 25 bps to a range of 3.75%-4.00%. The decision was unanimous and the statement noted that “inflation remains elevated.” In addition, the rate hike “will support a timelier return to 2% inflation.”
Housing starts and building permits came in weaker thain expected in August. Housing starts declined 2.6% (MoM) to a three month low. The biggest weakness was seen in multi family housing starts which fell 22% for the month. Building permits, a leading indicator for housing construction also fell to a two month low (1.394 million annual pace). Housing continues to be impacted by mortgage rates which have reached the highest level since May 2025.
Weekly Market Recap — Global Equities Fall on War and Hawkish Fed Rate Hike
Equities:
The MSCI AC World Index fell for the second consecutive week after geopolitical tensions continued and the Fed delivered a hawkish rate hike. The losses were broad based but the emerging markets fell the least as they benefitted from the rise in commodity prices. Within the U.S., technology (i.e. Nasdaq) and large cap growth ended the week in positive territory after some positive company specific reports (e.g., Micron).
Fixed Income:
The Bloomberg Aggregate Index fell for the third consecutive week after the Fed raised rates for the first time since 2023 and suggested more rate hikes were ahead. TIPS were the worst performing fixed income sector as inflation expectations dipped lower after the Fed raised rates. Investment grade debt was the only sector to end positive for the week.
Commodities/FX:
The Bloomberg Commodity Index rallied for the third consecutive week led by precious metals and industrial metals. Copper led the industrial metals higher as Chinese demand accelerated. Gold rose for the first time in four weeks due to safe haven demand.
Footnotes: Data is as of September 18, 2026.
Data Source: FactSet Research Systems, Verdence Capital Advisors.
Frequently Asked Questions:
What did the Federal Reserve do with interest rates last week?
The Federal Reserve raised the federal funds rate for the first time since 2023, moving it to a range of 3.75% to 4.00%. The decision was unanimous, and the Fed said inflation has stayed above target for more than five years.
Why did the Fed raise interest rates now?
Fed leadership said inflation remains a bigger concern than the labor market and that the hike removes some monetary accommodation. Policymakers pointed to underlying inflation trends that have shown little improvement.
Will the Fed raise interest rates again this year?
Forecasts from Federal Open Market Committee members point to at least one more rate hike before year-end. History shows the Fed rarely stops after a single increase once a tightening cycle begins.
How long do Fed rate hike cycles usually last?
Going back to 1946, the median tightening cycle has run about 12 months, with the fed funds rate rising an average of 2.6 percentage points. Cycles since 1989 have lasted closer to 14 months with roughly 300 basis points of increases.
What does a Fed rate hike mean for the stock market?
Rate hike cycles have historically coincided with more subdued equity returns as markets adjust to higher borrowing costs. That does not point to a downturn on its own, but it can bring added volatility.
Does a Fed rate hike mean a recession is coming?
According to Verdence’s Chief Investment Officer, this rate hike looks more like an effort to unwind years of accommodative monetary policy than a warning sign for the economy or the bull market. Markets may see continued volatility into year end as rates settle higher.
How are bonds reacting to the Fed rate hike?
Fixed income markets have been under pressure following the hike, with broad bond indexes falling for three straight weeks. Inflation protected securities lagged as inflation expectations eased, while investment grade debt held up better than other sectors.
How is the Fed rate hike affecting mortgage rates and housing?
The 30 year mortgage rate has climbed to its highest level in more than a year, and housing data has softened as a result. Builder confidence, housing starts and building permits have all declined in recent readings tied to higher borrowing costs.
What historical pattern does the current rate hike follow?
Since 1946, the Fed has rarely raised rates just once. The only true one and done hike came in 1997 under Alan Greenspan. Most cycles, including this one, tend to involve a series of increases rather than a single move.
What should investors watch after the Fed’s first rate hike?
Investors may want to watch for additional rate hikes, continued market volatility and pressure on rate sensitive sectors like housing. Verdence’s Weekly Insights breaks down what past tightening cycles suggest for portfolio positioning into year end.
